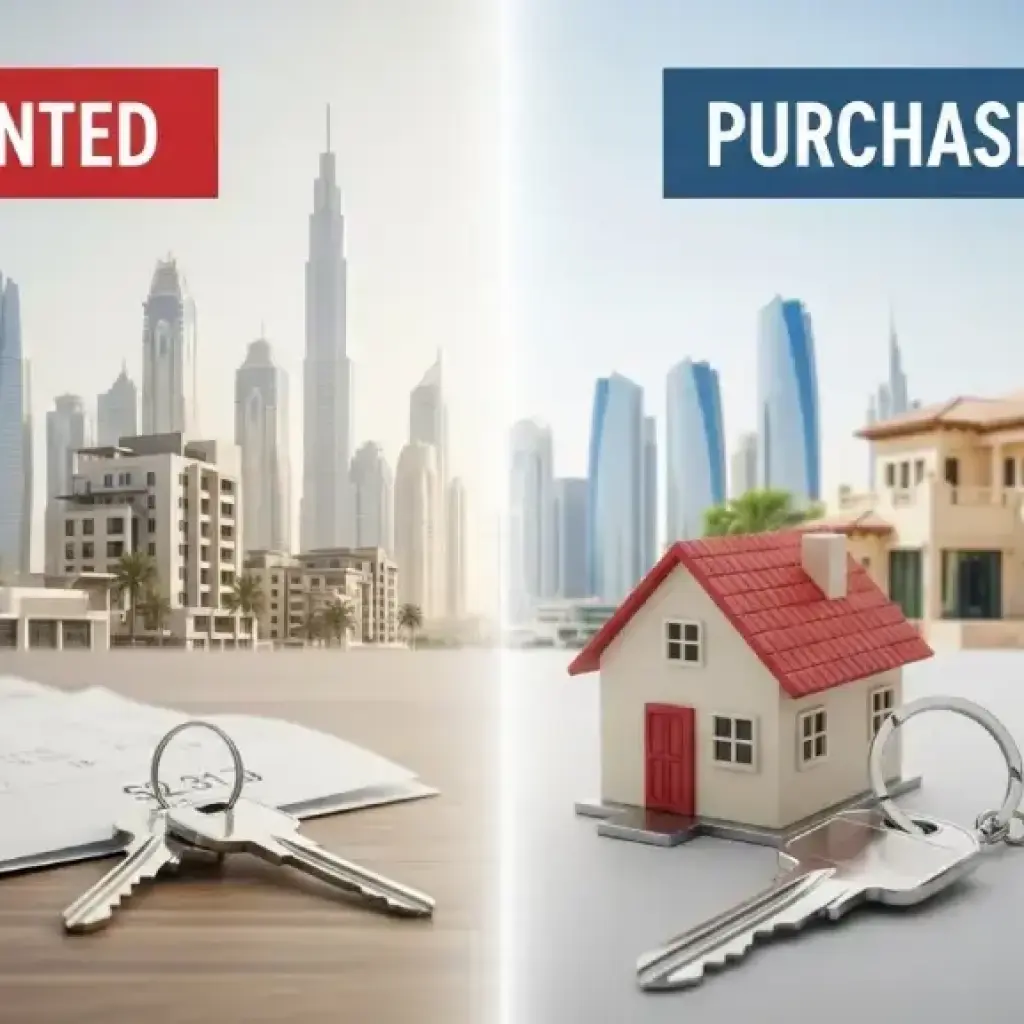
The decision to rent or buy a home represents the single largest financial choice an expatriate will make in the UAE. For many years, renting offered flexibility, but current market trends—including significant rent surges, stabilizing property prices, and incentives like the Golden Visa—have begun to tilt the financial scales in favor of long-term residents buying a home.
This guide provides an accurate, number-driven 5-year financial projection for both renting and buying a mid-market apartment in Dubai, focusing on current regulatory fees and a clear break-even analysis.
Part I: Defining the Scenario & Key Assumptions
We use a standard expat profile to ensure a comparable projection. The financial outcomes are based on these critical, conservative assumptions:
- Expat Profile: Gross Monthly Salary of AED 30,000, easily qualifying for financing.
- Stay Duration: 5 Years (the critical timeline for assessing the financial break-even point).
- Location Focus: A liquid, mid-range apartment community (e.g., JLT, Dubai Marina).
- Property Values:
- Initial Annual Rent: AED 100,000 (1-bedroom).
- Initial Purchase Price: AED 1,800,000 (2-bedroom).
- Inflation & Appreciation: A prudent long-term average of 5.0% Annual Growth for both rent and property value.
- Financing Basis: We use the standard maximum expat financing for a property under AED 5M:
- Loan-to-Value (LTV): 75%
- Down Payment Required: 25% of the property price.
- Assumed Mortgage Rate (Fixed): 4.24%.
Part II: The Cost of Renting Over 5 Years
Renting offers a low barrier to entry, but the payments are a non-recoverable expense.
A. Initial Capital Outlay (Low Barrier)
The initial cash required is minimal and covers mandatory deposits and fees:
- Refundable Deposits: Includes the Security Deposit (approx. 5% of rent, AED 5,000) and the DEWA/ADDC Deposit (approx. AED 2,000).
- Non-Refundable Fees:
- Agent Commission: Around 5% of annual rent (approx. AED 5,000).
- Ejari Registration: Mandatory RERA fee (approx. AED 250).
The Total Initial Cash Required is only about AED 12,250.
B. The Cumulative Non-Recoverable Cost
Assuming the 5% annual rent increase, the financial outlay becomes substantial:
- Rent Escalation: The annual rent grows from AED 100,000 in Year 1 to AED 121,551 in Year 5.
- Total Rent Paid: The cumulative rent paid over the five years amounts to AED 552,564.
- Final Position: The renter's total Non-Recoverable Cost (rent + non-refundable fees) reaches approximately AED 585,064 after 5 years. The expat is left with zero equity gain and faces a higher expense for Year 6.
Part III: The Cost of Buying Over 5 Years
Buying requires a high liquid investment upfront but converts payments into equity building and wealth.
A. The Upfront Capital Barrier (The Largest Outflow)
Due to the 75% LTV regulation, the expat needs to raise an estimated AED 587,810 upfront for the AED 1.8 million property. This capital covers:
- The Down Payment: 25% of the property price (AED 450,000).
- DLD Transfer Fee (Dubai): The mandatory 4% of the property price (AED 72,000).
- Mortgage Fees: Bank processing fees, valuation fees, and the DLD Mortgage Registration Fee (0.25% of the loan amount).
- Agent & Conveyance Fees: Broker commission (2% + VAT) and Trustee/Conveyance charges.
B. Monthly Ownership & Operating Costs
The expenses shift from escalating rent to fixed charges:
- Monthly Mortgage Payment (EMI): $\approx$ AED 8,110. This is for the AED 1.35 million loan, and is fixed during the initial rate period.
- Annual Service Charges: Estimated at AED 18,000 (common for a 2BR apartment).
- Annual Insurance: Mandatory life and property insurance (estimated at AED 6,000).
The Total Cash Outflow for operating costs and mortgage payments over five years is approximately AED 618,600. Combining this with the upfront fees, the buyer's cumulative outflow is AED 1,206,410.
C. Equity Build and Net Position
The financial benefit is realized through two factors:
- Appreciation: The property value increases to AED 2,297,306 after five years, a gain of AED 497,306.
- Principal Repaid: The buyer pays down approximately AED 115,000 of the loan principal, building direct equity.
D. The Net Financial Result (Post-Sale)
Upon selling the property in Year 5, the buyer realizes a significant gain:
- Gross Sale Proceeds: AED 2,297,306 (Year 5 Value).
- Deductions: Mortgage Balance (approx. AED 1,235,000) and Selling Fees (estimated 6% of sale price, approx. AED 137,838).
- Net Financial Gain: After all fees and repayment, the buyer generates a Net Financial Gain of approximately AED 452,000 over the five-year period.
Part IV: The Final Comparison & Break-Even Point
The financial difference after five years is dramatic:
- Renter's Position: An estimated AED 585,064 loss with no asset.
- Buyer's Position: An estimated AED 452,000 gain after covering all expenses and selling costs.
The financial break-even point—where the cumulative cost of buying equals the cumulative cost of renting—is achieved at around 4 years, assuming the 5% appreciation holds. The buyer's decision is validated primarily by the substantial equity and appreciation built.
Conclusion: A Strategic Wealth-Building Tool
For expats with job stability and a long-term plan of five years or more in the UAE, buying is the financially superior choice. It serves as a powerful tool for wealth creation and provides a fixed-cost hedge against rental inflation.
Key Challenges to Consider:
- High Liquidity: The buyer must have approximately AED 588,000 in liquid cash upfront.
- Job Security: Mortgage commitment requires high job security; regulations demand prompt settlement if employment is terminated.
- Abu Dhabi Advantage: Buyers in Abu Dhabi often benefit from a lower Property Transfer Fee ($\approx 2\%$) compared to Dubai's mandatory 4%, which slightly eases the upfront financial burden.
Would you like me to develop a follow-up post detailing strategies for new expats to manage the high upfront costs of buying in Dubai?